 Virtually all Nova Scotians are required to connect to NS Power. If we are connected to the grid then we have to pay a Base Charge of 20.08 per month, even if we have more than enough solar to completely power our homes. They are the last remaining monopoly in this province, and with them we are seeing a power rate increase of about 3.2% each year. The history of power increases, over the past 25 years, which is about 3.2% per year, can be seen here:
NS Power has recently filed an application with the Energy and Review Board (which is an updated form of the Utility and Review Board) for “Securitization”, which is a mechanism that can be used to reduce costs for customers and reduce future rate increases. That sounds great on the surface, but what does it really mean?
As I read through documents like this, I start with some questions, then get some more information and form more questions. I keep looking for more information until I have answered all of the questions that I have. I’ve tried to cover most of them here. If you have a question about the application or about my interpretation of it then please get in touch. There may be something that I have overlooked or misinterpreted.
What does the application show?
Unless otherwise noted, the rest of the data in this post comes from the application that NS Power has filed.
NS Power pays 6.59% interest on some of its assets (page 11). They are looking to hand off some of those assets, and other debts, to another organization and pay a lower interest rate on them. This is where it gets murky.
The list of assets and other debts (page 10) includes:
- 713 million for Thermal Assets (power plants)
- 27.6 million for financing costs on those assets
- 12.2 million on PHP Deferral (funds owed to Port Hawkesbury Paper)
- 20.2 million on IESO deferral (funds owed to the Independent Energy Systems Organization)
- 149.6 million as from a fuel account receivable
- 64.9 million as a fuel adjustment mechanism prepayment
- 12.5 million in financing fees
… for a total of $1 billion dollars to be financed.
NS Power has defined securitization (page 7) as “a complex commercial transaction which removes assets from a utility’s balance sheet and restructures the assets into debt, which is then refinanced in a bond issuance or other type of securities”.
Debt Consolidation
I assume that most of us are familiar with the concept of debt consolidation, but it’s the starting point for the NS Power discussion so it’s worth mentioning.
In our homes, when we have a lot of bills to pay and our income or cash flow doesn’t support all of them, we can consider consolidating debts.
Let’s assume that we pay $200 per month each for three different bills, for a total of $600 per month. We could choose to consolidate those debts into a new loan (for example) and have a single payment. Instead of paying $600 per month in total we would pay $300 per month. This helps our monthly cash flow, but the tradeoff is that it will take us longer to pay off and we will pay more interest overall.
NS Power seems to be asking for the opposite of debt consolidation.
They seem to be asking to take the one debt, at 6.59%, and split it into two debts. The first portion would be paid at 6.59%, but on a lower principal amount, and the second would be the result of the securitization and would be paid at a lower interest rate. The interest rate is included in Appendix B (page 53) which is confidential and hasn’t been shared with us.
What has been shared with us is what this would look like on our power bills. Nothing would be removed from our power bill (NS Power still has to pay the remainder of their debt). A rider would be added to our power bill to cover this $1 billion amount. This rider would be an increase of 3.9% on our bill, and it would stay on our power bill until the $1 billion is paid off. They estimate a payoff time of 30 years.
At the end of 30 years, the utility would have less debt, and the promise is that the 3.9% rider would be removed from our power bills. After that point, we would see less of an increase in the power rates. In 30 years.
How much is the rider, and who pays it?
NSPI needs a predictable revenue to cover the debt payments, and the formula, below (page 29) is their proposal.
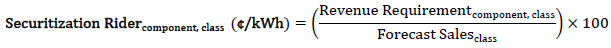
The rider is based on a “Revenue Requirement” based on the component class, divided by the “Forecast Sales”. Let’s look at each of these numbers so that we know what we might be paying.
Appendix D of the proposal discusses the rates for each customer class. That hasn’t been shared with us.
Appendix F discusses how the rate is calculated. The rate is non-bypassable and is imposed on all customer bills. This is in addition to the Base Charge that each of us already pay for. This applies to “all customers receiving electrical service (including transmission, distribution, or other services)” (Page 80). If you connect to the grid then you will have to pay this charge, since you will be receiving transmission and distribution services. In their proposal (page 83) they ask that the Base Charge is increased from 20.08 to 21.04, and that the power rate is increase from 18.324 per kWh to 19.067.
Will industrial or commercial customer be paying more than residential users? Are any of these fixed amounts, or are they based on a percentage of our bill or the kWh used? We don’t know. That is most likely described in Appendix D.
So what happens to the assets and other debt that we have paid off? Who owns that? NS Power.
NS Power proposes setting up a new “bankruptcy-remote limited partnership (LP)” (page 38) to hold the assets, which is wholly owned by NS Power. The assets, and the debt for those assets, would be transferred to the new LP. NS Power would use the funds from the new 3.9% rider to pay the debt off. When the debt is paid off, the LP and the assets would still exist, we would have “saved” $265.6 million in financing charges instead of paying the above mentioned 6.59%
Since the LP is wholly owned by NS Power, the assets would remain the property of NS Power.
This is similar to HRMs Climate Action Tax…
The Climate Action Tax was put in place in 2022 as a 10 year 3% increase in our property taxes in order to pay for upgrades to our municipal buildings. The concept was that these upgrades would improve energy efficiency and, therefore, reduce the ongoing costs. To finance those upgrades, we needed to pay 3% more. (I voted against this.)
At this point the CAO, finance staff, the Mayor, and many of the Councillors have changed. By the time 10 years is up (another 6 years) we will see more changes. The 10 year term will be forgotten, and the 3% increase will be the norm. I don’t expect that it will ever be removed.
With this mechanism, we will see our power bills increase by 3.9%, and there will be a rider included on our power bills. In 30 years nearly everybody involved will be retired and we will have a whole new set of people in NS Power, the Energy and Review Board, and the provincial government, but we will still be paying that extra 3.9% that nobody has any memory of. I don’t expect it to be removed from the power bill.
My Conclusion – I can’t support it
In other places, the securitization process has been successful at reducing the increase in rates. I understand what NS Power is trying to do. After 30 years the rate increases will be less.
In the mean time, however, we are looking at a 7% increase in our power bills for 2027. That is too much. And that 3.9% addition may never go away.
I can’t support this proposal.